Commercial Real Estate Investment: Identifying, Analysing and Enhancing High-Potential Assets
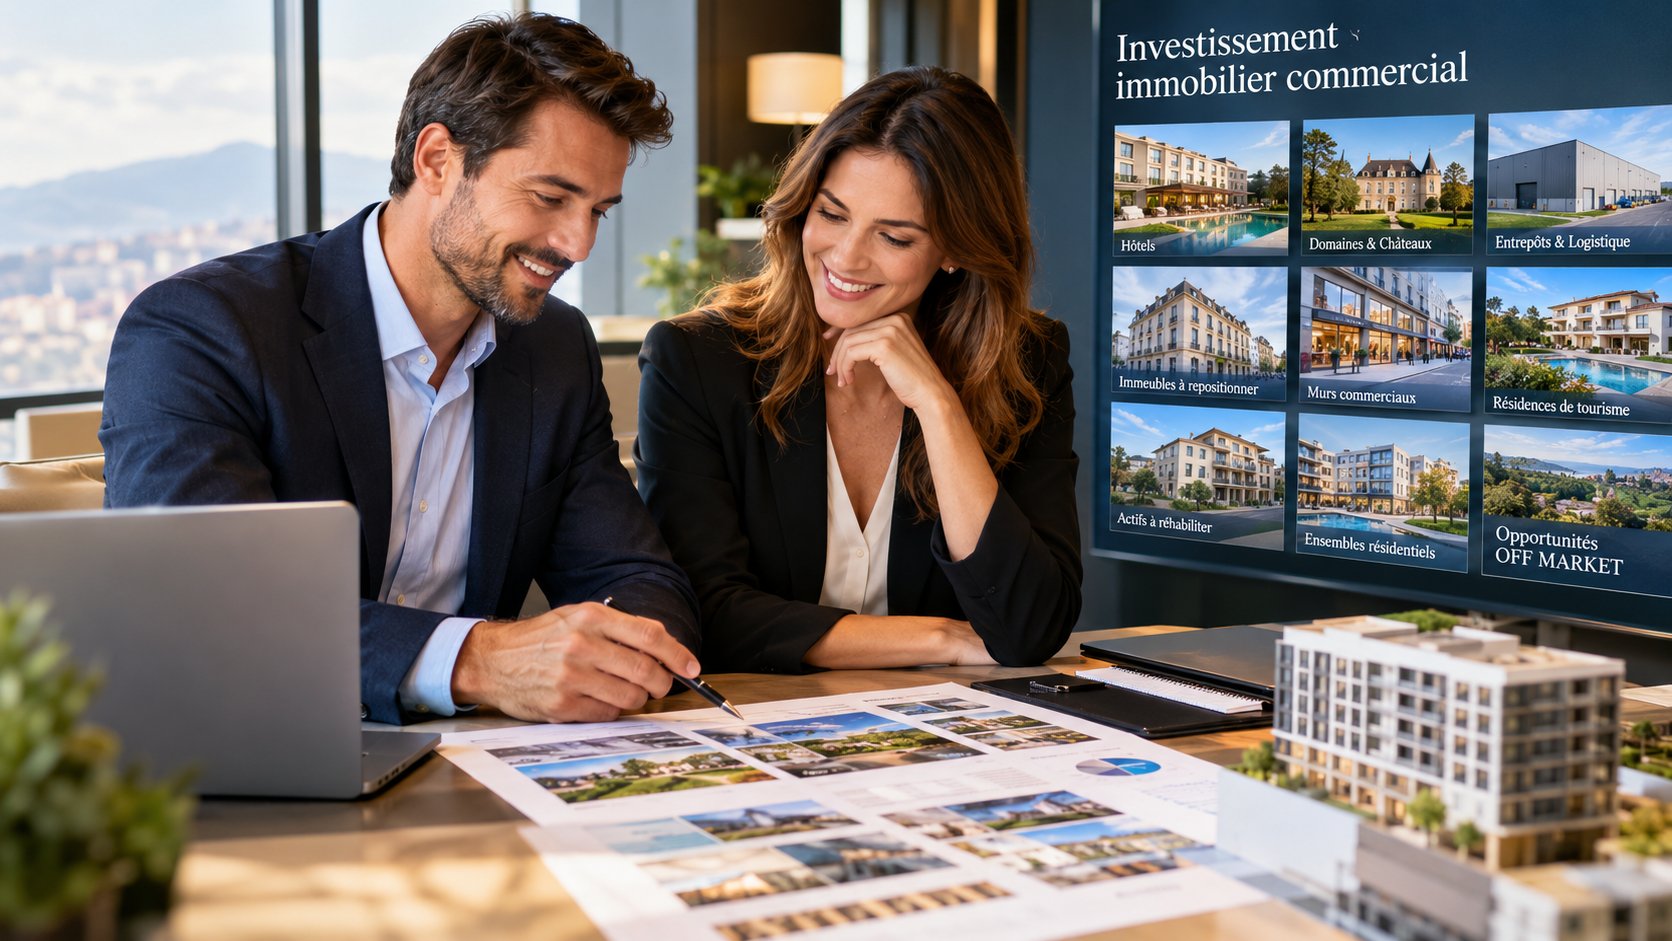
Hotels, estates, châteaux, warehouses, buildings, commercial premises and OFF MARKET opportunities in France and internationally.
Commercial real estate investment offers a far wider universe of opportunities than traditional residential property.
Hotels, character estates, châteaux, logistics warehouses, office buildings, commercial premises, managed residences or buildings to rehabilitate: these assets have very different characteristics, acquisition strategies and value-creation prospects.
A significant share of these opportunities is negotiated OFF MARKET, meaning outside traditional marketing channels, without necessarily being publicly advertised on property portals.
These confidential transactions may involve owners wishing to sell their assets discreetly, investors preparing a portfolio rebalancing, or deals that require a targeted approach to qualified buyers.
For the investor, the challenge is therefore not only to identify a property available on the market. It is also about knowing how to access the right opportunities, analyse their economic potential, anticipate technical and financial constraints, and define a value-creation strategy.
In this series dedicated to commercial real estate investment, we explore the main asset classes, their specific features, advantages and risks, and the essential criteria to examine before any acquisition.
Our approach is based on one conviction: the quality of an investment depends as much on the relevance of the selected asset as on the quality of its analysis and the support provided.
1. Hotels and hospitality establishments
How the investment works
Hotel investment consists of acquiring an establishment intended for tourist or business accommodation.
The transaction may cover the property walls only, the business (fonds de commerce), or the combined real estate and business.
Several strategies are possible:
- Acquiring a hotel that is already operating.
- Acquiring an establishment to renovate.
- Repositioning an ageing hotel.
- Upgrading an establishment to a higher category.
- Acquiring the walls and leasing them to an operator.
Advantages
- Potentially significant income when operations perform well.
- Opportunity to increase the asset's value through renovation or repositioning.
- Diversified clientele: tourism, business, events.
- Potential to develop additional services.
Disadvantages
- Complex day-to-day operational management.
- Dependence on tourist and economic activity.
- High staff and operating costs.
- Regular investment in renovation and compliance upgrades.
- Sensitivity to seasonality.
What should the buyer look at?
- Location and tourist appeal.
- Number of rooms and occupancy rate.
- Average daily rate (ADR).
- RevPAR (revenue per available room).
- Turnover and EBITDA (EBE).
- Technical condition of the building.
- Classification and applicable authorisations.
- Reputation and commercial potential.
- The establishment's performance history.
Investment example
A 25-room hotel is offered at €1,500,000 for the walls and the business.
The buyer is considering a €300,000 renovation, followed by a commercial repositioning to raise the average nightly rate and the occupancy rate.
The analysis must compare current profitability with the post-works scenario, factoring in acquisition costs, capital expenditure, operating costs and financing.
Point of caution: always distinguish the real estate return from the performance of the hotel business itself.
2. Estates, châteaux and character properties
How the investment works
These assets include prestige properties, rural estates, châteaux, wine estates, event venues and property complexes with substantial land holdings.
They can be operated through a variety of activities:
- Hotels and guest rooms (chambres d'hôtes).
- Weddings and events.
- Seminars and receptions.
- Tourism and accommodation.
- Agricultural or wine-growing activities.
- Private and seasonal rentals.
Advantages
- Often highly distinctive assets.
- Potential for long-term capital appreciation.
- Diversified income streams.
- Ability to develop several activities.
- Appeal to a specific clientele.
Disadvantages
- Upkeep can be costly.
- Significant restoration works.
- Heritage and environmental constraints.
- Dependence on operating capability.
- Sometimes lower liquidity on resale.
What should the buyer look at?
- Land area and building rights.
- Condition of the buildings and outbuildings.
- Existence of easements.
- Planning regulations.
- Any heritage protection.
- Commercial operating potential.
- Maintenance and renovation costs.
- Accessibility and appeal of the area.
- Resources and facilities available on the estate.
Investment example
A 5-hectare estate comprising a main house, several outbuildings and outdoor grounds is offered at €1,200,000.
The investor is studying the possibility of developing a reception, tourist accommodation and seminar business.
Profitability must not be assessed solely on the estate's heritage value, but on the real economic feasibility of operating it.
3. Warehouses and logistics assets
How the investment works
Warehouses and logistics buildings are used for storage, distribution, order preparation or industrial activities.
The investment may take the form of a buy-to-let acquisition or a restructuring and re-letting operation.
Advantages
- Possibility of signing long-term commercial leases.
- Relatively predictable rental income when the tenant is strong.
- Demand driven by storage and distribution needs.
- Potential to add value through technical upgrades.
Disadvantages
- Dependence on accessibility and location.
- Potentially long vacancy periods.
- Sometimes significant technical works.
- Building obsolescence.
- Environmental and regulatory constraints.
What should the buyer look at?
- Proximity to major roads and economic hubs.
- Usable floor area.
- Clear ceiling height.
- Floor load capacity and condition.
- Heavy goods vehicle access.
- Loading docks.
- Electrical capacity.
- Regulatory compliance and fire safety.
- Tenant quality and lease terms.
- Condition of the roof and technical installations.
Investment example
A 3,000 m² warehouse is offered at €800,000.
After €100,000 of fees and works, the total investment reaches €900,000.
With annual rent of €90,000, the gross yield on total cost comes to 10%.
This figure must then be adjusted for non-recoverable charges, potential vacancy, maintenance and financing costs.
4. Buildings to reposition
How the investment works
Real estate repositioning consists of acquiring a building whose current use, technical condition or layout no longer fully matches its potential.
The aim is to create value through:
- A full renovation.
- A reconfiguration of the spaces.
- Improved marketing and letting.
- A change of use, where permitted.
- A division into several units.
- Converting offices into housing, subject to feasibility.
Advantages
- Significant value-creation potential.
- Opportunity to acquire assets at a discount.
- Several possible exit strategies.
- Optimisation of floor area and uses.
Disadvantages
- Risk of exceeding the works budget.
- Administrative delays.
- Uncertainty over permits.
- Commercial risk on resale or letting.
- Capital tied up during the works.
What should the buyer look at?
- Legal and planning status.
- Current designated use and actual use.
- Options for a change of use.
- Structural condition of the building.
- Cost of works.
- Floor area that can genuinely be monetised.
- Rental and resale markets.
- Projected timeline of the operation.
- Any co-ownership constraints.
Investment example
A vacant office building is acquired for €900,000.
A €350,000 restructuring programme is planned.
The investor is studying a conversion into housing or mixed-use premises.
The acquisition decision must rest on a technical, administrative and financial feasibility study, as well as a prudent estimate of the exit value.
5. Commercial premises and professional units
How the investment works
The investor acquires commercial or professional premises in order to collect rent.
This may be a shop, a restaurant, a medical practice, an independent business or a retail complex.
Advantages
- Recurring rental income.
- Possibility of long-term commercial leases.
- Value driven by the quality of the location.
- Diversification of a property portfolio.
Disadvantages
- Risk of tenant departure or default.
- Dependence on local commercial activity.
- Refurbishment works between tenancies.
- Rental vacancy.
- Lease terms can be complex to negotiate.
What should the buyer look at?
- Location and visibility.
- The tenant's business.
- The operator's financial strength.
- Amount and regularity of rent payments.
- Remaining lease term.
- Allocation of charges and works.
- Rental history.
- Market rental value.
- Permitted use and possible activities.
Investment example
A let commercial unit is offered at €450,000.
The annual rent is €36,000.
The gross yield on the purchase price is 8%, before fees, charges and tax.
The analysis must in particular verify that the rent is in line with the market and that the tenant's position is sufficiently solid.
6. Investment buildings and residential portfolios
How the investment works
The acquisition covers an entire building or a group of homes intended for rental.
The investor may keep the existing tenants, gradually renovate the units or optimise letting.
Advantages
- Multiple rental income streams.
- Rental risk spread across several units.
- Potential to add value through renovation.
- Holistic management of the asset.
Disadvantages
- Heavier rental management.
- Works on both common and private areas.
- Risk of unpaid rent and vacancy.
- Energy and regulatory constraints.
What should the buyer look at?
- Rental status of each unit.
- Rents and any arrears.
- Condition of the common areas.
- Technical surveys.
- Energy performance.
- Works already voted or to be planned.
- Charges and taxation.
- Local rental market.
- Compliance of the homes and installations.
Investment example
A building with 10 apartments is offered at €1,100,000.
Potential annual rents are estimated at €84,000.
The investor is studying the possibility of gradually renovating the units to improve their rental appeal and the overall value of the building.
7. Tourist residences and managed assets
How the investment works
This involves acquiring a property or a complex intended for accommodation or service activities: tourist residences, student residences, senior residences or serviced residences.
The investment may cover the walls, an individual unit or an entire complex.
Advantages
- Ability to delegate operations to an operator.
- Contractual income depending on the structure chosen.
- Market driven by specific accommodation needs.
- Potentially simplified management for the owner.
Disadvantages
- Dependence on the operator's strength.
- Risk of lease renegotiation.
- Dependence on the operator's business model.
- Resale can be more complex.
What should the buyer look at?
- The operator's financial strength.
- Lease terms.
- Rental history.
- Allocation of charges and works.
- Occupancy rate of the residence.
- Length of commitment.
- Resale value outside the managed scheme.
- Obligations of the owner and the operator.
Investment example
An investor acquires a group of managed units within a tourist residence.
The analysis focuses as much on the property value as on the profitability of the operation and the operator's ability to honour its commitments.
8. Assets to rehabilitate and brownfield sites
How the investment works
These assets are often characterised by poor condition, no occupancy or a use that has become obsolete.
They can offer significant transformation potential, provided the technical, environmental and administrative constraints are well managed.
Advantages
- Purchase price sometimes discounted.
- Value-creation potential.
- Wide range of transformation strategies.
- Opportunity to meet new real estate needs.
Disadvantages
- High technical risk.
- Possible soil contamination.
- Decontamination costs.
- Uncertainty over timelines and permits.
- Sometimes substantial equity requirements.
What should the buyer look at?
- Structural survey.
- History of the site.
- Environmental studies.
- Possible presence of contamination.
- Planning feasibility.
- Full rehabilitation cost.
- Exit value.
- Length of the financial holding period.
- Required administrative authorisations.
Investment example
A former 2,500 m² industrial building is offered at €500,000.
The investor is studying a conversion into business premises or professional space.
Profitability will depend mainly on the actual rehabilitation cost, the permits obtained and rental demand once the works are complete.
9. How to calculate the return on a real estate investment
An acquisition should never be assessed solely on the asking price and the advertised rent.
The total cost of the operation must be taken into account.
Total acquisition cost
It includes in particular:
- Purchase price.
- Acquisition costs.
- Any agency or advisory fees.
- Works.
- Technical and administrative costs.
- Financing costs.
- Contingency provision.
Gross yield
Gross yield = annual rent / acquisition cost × 100.
Net yield
Net yield = annual income after operating costs / total cost × 100.
Cash flow
Cash flow measures what remains after operating expenses, loan repayments and any other outgoings taken into account.
IRR
The internal rate of return measures the overall performance of an operation, taking into account cash flows over the entire holding period and the resale price.
It is particularly useful for renovation, repositioning and property-trading (marchand de biens) operations.
Worked example: acquiring a warehouse
Consider a warehouse acquired as a rental investment.
Gross yield:
€90,000 / €900,000 × 100 = 10%
Net yield before financing and tax:
€78,000 / €900,000 × 100 = 8.67%
A fundamental principle
A high yield does not necessarily mean a good investment.
An asset showing a 10% gross yield may carry more risk than one showing 6% if its technical condition is poor, its location is fragile or its tenant has weak creditworthiness.
The quality of the asset, the security of income and liquidity on resale must always be built into the analysis.
10. How to finance your acquisition with a bank
Bank financing is a decisive factor in the success of a real estate operation.
The bank generally analyses several elements:
- The investor's financial profile and experience.
- Amount of equity contribution.
- Value and quality of the property.
- Current or projected rental income.
- Repayment capacity.
- Level of debt.
- Guarantees offered.
- Consistency of the business plan.
The main financing solutions
Professional real estate loan
Suited to acquiring property intended for a professional or rental activity.
Financing through an SCI or a dedicated company
Allows the ownership of the asset to be structured according to the project, the partners and wealth-planning objectives.
Financing a property-trading (marchand de biens) operation
Based on a specific analysis of the acquisition cost, works, marketing period and projected margin.
Financing including works
Can cover both the purchase price and a works budget, subject to the bank's approval and a sufficiently documented file.
Bank financing example
Assume a total investment of €900,000 financed as follows:
- Personal contribution: €270,000.
- Bank loan: €630,000.
- Term: 20 years.
- Hypothetical rate: 4% excluding insurance.
The monthly repayment would be approximately €3,818, or about €45,816 per year.
With annual income before financing of €78,000, annual cash flow would be approximately €32,184, before tax and other costs not included in the simulation.
This simulation is for illustration only and does not constitute a bank financing offer.
How to present your bank file
A serious file should include:
- Presentation of the investor.
- Description of the asset.
- Price and total cost of the operation.
- Market study.
- Income estimate.
- Works budget.
- Financing plan.
- Cash-flow forecast.
- Exit strategy.
It is important to plan several scenarios: conservative, base case and optimistic.
The aim is to demonstrate that the operation remains viable even if rents come in below forecasts or the works are delayed.
11. The 10 essential checks before acquiring an asset
Before any acquisition, an informed investor should in particular check:
- The legal situation and title deeds.
- The planning situation and permits.
- The technical and structural condition.
- The mandatory regulatory surveys.
- Any environmental risks.
- The rental situation and leases.
- The local property market.
- The total cost of the operation.
- The feasibility of financing.
- The prospects for value creation and resale.
It is also advisable to surround yourself with competent professionals: notary, chartered accountant, lawyer, architect, engineering consultancy and technical specialists depending on the nature of the asset.
12. OFF MARKET opportunities: accessing confidential assets
The OFF MARKET segment holds a special place in commercial real estate investment.
Unlike properties advertised on traditional platforms, these opportunities are presented in a targeted way to buyers or investors likely to match the profile of the deal.
They may include:
- Hotels and hospitality establishments.
- Estates and prestige properties.
- Property portfolios held by private investors.
- Warehouses and industrial buildings.
- Vacant buildings or buildings to restructure.
- Commercial premises and professional units.
- Assets requiring a repositioning operation.
Why do some owners prefer OFF MARKET?
Several reasons can explain this choice:
- Keeping a sale confidential.
- Avoiding public marketing.
- Limiting viewings to qualified buyers.
- Controlling how information is shared.
- Favouring a direct approach to targeted investors.
What should the buyer check?
An OFF MARKET opportunity does not automatically mean a financially advantageous one.
The investor must apply the same analytical rigour as for a conventional acquisition:
- Verify the identity and standing of the seller.
- Confirm that the property is genuinely available.
- Review the legal and technical documents.
- Compare the asking price with the market.
- Assess the works and the risks.
- Check the feasibility of financing.
- Define an acquisition and exit strategy.
Access to a confidential opportunity is a potential advantage, but only rigorous analysis can determine whether the investment makes sense.
13. Everest Maison & Conseil: a partner for your commercial real estate investment projects
To identify property opportunities, including OFF MARKET ones, or to bring an investment project to fruition in France and internationally, you can call on Everest Maison & Conseil and benefit from support tailored to your search and your objectives.
Everest Maison & Conseil
Identifying opportunities. Supporting acquisitions. Contributing to value creation.
Commercial real estate investment | OFF MARKET opportunities | France & International
A commercial real estate investment project?
Contact Us